Translation of an article written and signed in French by Sandy MASCART, for information. Only the French version is authoritative. Read the French page
Advice
Mortgage guides: borrowing capacity, PTZ, insurance, rental investment
Borrowing capacity, PTZ, insurance, buy-to-let, buyouts, bridging loans: the answers, topic by topic.
145 articles.
Mortgage basics
See all 21 articles-
Mortgage basics
Works voted on in a co-ownership before your purchase: who pays, and on what date
Works voted on before the sale of an apartment: what the 1967 decree places on the seller or the buyer, and what the preliminary sale agreement can change.
-
Mortgage basics
Acting as guarantor for a relative’s mortgage: what you are actually signing
Acting as guarantor means paying a relative’s mortgage from your income and assets if they cease to pay. What you must check before signing.
-
Mortgage basics
APR: How to read it and compare two loan offers without making a mistake
The APR brings together interest, file fees, guarantee, required insurance and intermediary fees. What it contains, what it ignores, how to compare.
-
Mortgage basics
Building with a CCMI: financing the land and the house in the correct order
One loan for land and house: the order of signatures, the documents the bank requires before its offer, and funds released as the build progresses.
-
Mortgage basics
Buying in co-ownership: securing the loan, the shares and the exit
Buying jointly in co-ownership: what the bank requires, how to set fair shares, and how to exit while the loan is still running.
-
Mortgage basics · Comparison
The cooling-off period for the preliminary sale agreement or the reflection period on the loan offer: no longer confusing them
Cooling-off: renouncing the purchase. Reflection: not accepting the loan too soon. Start, form and effects of both periods, so you lose nothing.
Borrowing capacity, income and budget
See all 12 articles-
Borrowing capacity, income and budget · Guide
Calculating the monthly repayment on a mortgage: the formula in six steps, and its blind spots
Calculate the monthly repayment on your mortgage in six steps, then see what the formula omits: insurance, guarantee, fees, APR and usury.
-
Borrowing capacity, income and budget
How much can I borrow alone with €2,500 per month?
Alone with €2,500 of income per month: what determines your borrowing capacity, the constraint that decides, and where to find room if the calculation stalls.
-
Borrowing capacity, income and budget
What salary do you need to borrow €200,000 in Lyon?
What salary to borrow €200,000: calculating the minimum income, and why disposable income, term and insurance can weigh as heavily as the cap.
-
Borrowing capacity, income and budget
Bonuses, commissions, variable pay: how do you get the bank to count them?
A bonus or a commission counts if it is written down, regular and proven over several years. The documents to gather and the table to prepare.
-
Borrowing capacity, income and budget
Financing a second home: what the bank counts, and what it does not
The same debt-to-income limit, no rental income offset, no subsidised loan: what the bank counts for a second home, and the documents to prepare first.
-
Borrowing capacity, income and budget
Marital regime and borrowing: who signs, who is bound, and what the bank requires
Community of property, separation of property, PACS: how your regime affects the loan. Who signs, which assets secure the debt, and which documents to provide.
First-time buyers
See all 11 articles-
First-time buyers · Guide
Buying at auction with a mortgage: what must be settled before bidding
Bidding with a mortgage: ten questions before the session, the real time a loan takes, and what to do when the payment deadline is too short.
-
First-time buyers · Checklist
Ancillary costs of a property purchase: the complete list of what is paid in addition to the price
Deed costs, credit costs, property costs, installation costs: the four categories of costs added to the price, who calculates them, and who pays them.
-
First-time buyers
Family loan for the deposit: how to draft it, declare it and present it to the bank
A family loan complements the deposit, but the bank counts it as a debt. How to draft it, declare it, choose the repayment schedule and present it.
-
First-time buyers
Notary fees for new-build properties: what you are actually paying, and when?
In new builds, the tax falls, not the notary’s share. What remains due, the cases where the reduced rate does not apply, and when everything is paid.
-
First-time buyers
Unlocking your PEE or PER to buy your main residence: a step-by-step guide
Your PEE, and under certain conditions your PER, can be unlocked to buy your main residence: documents, timeline, net amount, and how the lender interprets it.
-
First-time buyers
Donation from parents for the down payment: ensuring the gift is recognised without delaying the application
Family gift for the down payment: documents proving the origin of funds, what must be declared, and what to ask the notary before the transfer.
Assistance schemes, PTZ and local schemes
See all 11 articles-
Assistance schemes, PTZ and local schemes
Reduced VAT for new-build purchases in Lyon and Villeurbanne: conditions, neighbourhoods, resale
Reduced VAT on new builds in Lyon and Villeurbanne: neighbourhoods and surrounding band, income and price ceilings, principal residence, resale.
-
Assistance schemes, PTZ and local schemes
PSLA and shared ownership: preparing the financing for the option exercise
In shared ownership, the loan is applied for when the option is exercised. What the bank reviews that day, and how to prepare your file from move-in.
-
Assistance schemes, PTZ and local schemes
PTZ 2026: How to apply, required documents and the right timeline
The PTZ is applied for at the bank, with the main loan. The documents to prepare, the date that fixes your entitlement and the timeline errors to avoid.
-
Assistance schemes, PTZ and local schemes
PEL and CEL: Does the loan entitlement still hold any value today?
Your loan entitlement’s rate was fixed the day the plan opened. Where to read it, what to compare it with, and the decision rule in three questions.
-
Assistance schemes, PTZ and local schemes
Social Access Loan and Conventional Loan: What They Offer, and What They No Longer Offer
The PAS caps the interest rate; it no longer opens access to the APL for buyers. What remains, what closed and by which text, what the scheme leaves unchanged.
-
Assistance schemes, PTZ and local schemes
Does the PTZ count towards your debt-to-income ratio? Can it be used as a down payment?
Yes, the PTZ counts in your debt-to-income ratio from the end of the deferral; no, it does not replace a down payment. What the lender calculates.
Buy-to-let investment
See all 15 articles-
Buy-to-let investment
Tourist furnished accommodation in Lyon: what the bank looks at, what the City imposes
Short-term letting in Lyon: registration, change of use, compensation in the hyper-centre, and the rent a lender may retain.
-
Buy-to-let investment
Rent control in Lyon and Villeurbanne: the rent the lender will take into account
Rent control in Lyon and Villeurbanne: where it applies, how to read the capped reference rent, and the rent the lender will take into account.
-
Buy-to-let investment
Financing a bare ownership purchase: the loan for a property that generates no income
Bare ownership on credit: no rental income against the loan. Term aligned with the usufruct, security, charges, taxation, exit: what the bank checks.
-
Buy-to-let investment · Guide
SCPI financing: what the lender checks before funding units
Few lenders finance SCPI units. Loan regime, income considered, security, fees, liquidity: what they verify and how to prepare.
-
Buy-to-let investment
Buying a rental property: building a file the bank can read
A rental property is financed through a mortgage and assessed as an asset: tenancy status, technical condition, cash flow. The documents that decide.
-
Buy-to-let investment
Buying an occupied property: financing a home sold with its tenant
A let property is purchased with its tenancy: the rent the lender retains, the documents to require from the seller, and the timeline if you wish to occupy it.
Buyouts, renegotiation, bridging loans
See all 12 articles-
Buyouts, renegotiation, bridging loans · Guide
Debt consolidation with a mortgage: applicable regime, true cost and alternatives
Consolidating a mortgage and consumer loans: the applicable regime, the true total cost, and the lighter solutions to try first.
-
Buyouts, renegotiation, bridging loans
Long sale: how to finance a purchase when the deed is signed months after the preliminary sale agreement
Long sale: when to submit the mortgage application, how to keep a loan offer valid until the deed, and how the seller can do without a bridge loan.
-
Buyouts, renegotiation, bridging loans
Remortgaging in Lyon: the steps, in order, for changing bank
Having your mortgage taken over by another bank: documents, processing, offer, settlement of the old loan, and the pitfalls that cause a remortgage to fail.
-
Buyouts, renegotiation, bridging loans
Separation or divorce with a mortgage running: who pays what, and what to tell the bank?
Until the bank signs, you both remain liable for the whole loan. What to arrange as soon as you separate, and the order of the decisions after that.
-
Buyouts, renegotiation, bridging loans · Comparison
Adjusting, deferring or suspending instalments: getting through a difficult period without changing your loan
Adjusting, deferring or suspending instalments: what each clause really costs, the condition raised against you, and the written confirmation to get.
-
Buyouts, renegotiation, bridging loans · Guide
Release of mortgage: when it is required, what it costs, and when to avoid it
A registration lapses after the final instalment: the three cases where a release is required, the two where no deed is needed, and its real cost.
Borrower insurance
See all 18 articles-
Borrower insurance
Is borrower insurance mandatory? No, but the lender may require it: who decides what
No law requires you to insure a mortgage, but the lender may require it: what the lender decides, what you choose, and what to do in the event of a refusal.
-
Borrower insurance
Delegation of borrower's insurance: when to request it for a new loan?
For a new loan, the delegation of insurance is prepared before the offer: documents to request, order of procedures, what the bank cannot do.
-
Borrower insurance
“Your own profession” or “any profession”: the definition of incapacity that decides everything
Two wordings, two worlds: depending on your contract’s definition, the same period of work incapacity either triggers the cover or does not.
-
Borrower insurance · Guide
Borrower insurance guarantees: what death, total and irreversible loss of autonomy, total and permanent incapacity, permanent total disability and permanent partial disability actually cover
The five guarantees of loan insurance, in the order they apply: what triggers them, who decides, and the line in the policy document that settles it.
-
Borrower insurance
Continuity of cover: what you lose, or do not lose, when changing insurance
Changing your loan insurance does not reset any counter on the cover. What is carried over, what is not, and the clause to have written.
-
Borrower insurance · Guide
Death of a borrower: what the insurance covers and what remains the responsibility of the co-borrower
Who the insurance pays, what it does not cover, what remains to be paid by the surviving party, and the questions to ask the solicitor: the mechanics, in order.
Non-standard profiles
See all 11 articles-
Non-standard profiles
Borrowing while pregnant or on sick leave: your rights vis-à-vis the bank and the insurer
Mortgage while pregnant, on maternity leave or on sick leave: what the bank reads, what the insurer may request, and what the law prohibits.
-
Non-standard profiles
Company director or manager: making your income legible for a mortgage
Company director: the lender reviews your personal file and the company’s. The documents that make your income legible, and the commitments to declare.
-
Non-standard profiles
Listed on the FICP: removing your name from the register, then preparing your mortgage
While listed on the FICP, a mortgage is refused almost everywhere. Check the entry, regularise the situation, have the removal confirmed, then reapply.
-
Non-standard profiles
Parental leave and mortgage: borrowing at the right time, on the right income
Borrowing on parental leave remains possible: the lender assesses income on the day of review. Choosing the submission date, the documents, the insurance.
-
Non-standard profiles
Borrowing after 60: Removing the real obstacles, from insurance to term
There is no legal age limit for borrowing. After 60, three factors decide: the insurer, pension income and the insured amount.
-
Non-standard profiles
Expat or non-resident mortgage: borrowing in France from abroad
Tax residence, down payment, foreign-currency income, banks that accommodate, remote signing: what makes a non-resident application financeable in France.
My role, fees and transparency
See all 8 articles-
My role, fees and transparency
Reviews of a mortgage intermediary: what a review proves, and what it does not
A rating recounts the experience of other clients, not the professional's status. What the law requires of reviews, and what can be verified in a few minutes.
-
My role, fees and transparency
Relationships with lenders: what the law requires you to be told, and what this site publishes
Which banks does a mortgage intermediary work with? The four pieces of information the law requires them to provide, and the additional questions to ask.
-
My role, fees and transparency
Estate agents and mortgage lead generation: where referral ends and intermediation begins
Estate agencies: where the code draws the line between referring and intermediating in mortgage lending, and the five clauses that make an agreement clear.
-
My role, fees and transparency
What I do not do: consumer credit, reverse mortgage, standalone renovation loan
My mandate covers residential mortgage lending and debt consolidation. Where the boundary lies, why it exists, and who to turn to beyond it.
-
My role, fees and transparency
Can you put two mortgage intermediaries in competition and approach your bank at the same time?
Yes, it is permitted: consulting several intermediaries and keeping your bank, provided you avoid the duplication that causes your application to slip.
-
My role, fees and transparency
Intermediary fees: how much, who pays, and when
Free pricing, bank commission, nothing to pay before the funds are disbursed, impact on the APRC: what a mortgage intermediary really costs, and when.
The Lyon market and its financing
See all 15 articles-
The Lyon market and its financing
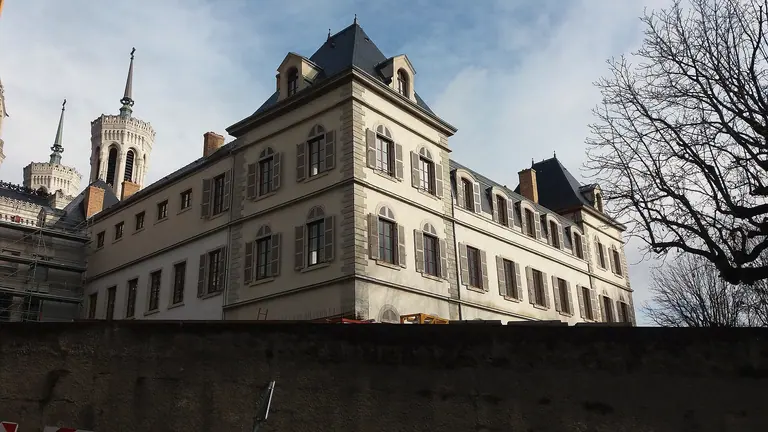
Mortgage in the 5th arrondissement of Lyon: Vieux Lyon, the hill and the plateau
Are you looking for a mortgage intermediary in Lyon 5th? Old co-ownership properties, Vieux Lyon, the balmes of Fourvière, what the bank reads.
-
The Lyon market and its financing · Comparison
Buying in the Vallons du Lyonnais: what leaving the Métropole changes for your financing
Brindas, Grézieu-la-Varenne, Vaugneray and five other communes: zero-interest loan, transfer duties, planning, council tax. What leaving the Métropole changes.
-
The Lyon market and its financing
A house with land in the west of Lyon: what the bank reads, and what it does not read in a flat
Energy audit, sewage treatment, itemised works, soil survey, land division, swimming pool: what a lender reads about a house before financing it.
-
The Lyon market and its financing
Mortgage in Charbonnières-les-Bains: land, council tax, stations and risks
Are you looking for a mortgage intermediary in Charbonnières-les-Bains? Housing, PLU-H, council tax, stations, risks: what the municipality changes.
-
The Lyon market and its financing · Guide
Council Tax in the Lyon Metropolis: Reading Your Commune's Rate
Council Tax in Lyon and the Metropolis: reading the notice (base, rate, waste collection) and finding the rate voted by your commune, year by year.
-
The Lyon market and its financing
Mortgage in Écully: how the municipality affects your financing
Are you looking for a mortgage intermediary in Écully? Zero-interest loan in Zone A, purchase costs, council tax, rents in a tight market, risks.
Lenders, panel and loan offer
See all 11 articles-
Lenders, panel and loan offer
Mortgage amortisation schedule: how to read and check it yourself
Amortisation schedule: verify each line with three checks, read the interest, capital and insurance, and see the effect of an early repayment.
-
Lenders, panel and loan offer
Releasing the funds for a mortgage: who triggers it, when the money is transferred, and how to avoid a delay
The notary calls the funds, not you. What the lender checks before paying out, when to transfer your own contribution, and how to avoid a delayed release.
-
Lenders, panel and loan offer
Capped variable-rate loan: what the clause says, and what the cap does not protect against
Index, frequency, margin, cap: read the variable-rate clause of a mortgage in four lines, and identify what the cap does not protect against.
-
Lenders, panel and loan offer
FISE: the only document that makes two loan offers truly comparable
The FISE aligns two loan offers item by item. The reading order that avoids false discrepancies, and the three sections where the price is hidden.
-
Lenders, panel and loan offer
Mortgage guarantee: who issues it, and how to recover what is due to you
Lost commission, refundable mutual fund: who guarantees your loan, whom to write to after settlement, and how to recover what is due to you.
-
Lenders, panel and loan offer · Comparison
Online bank mortgage: for which applications is the branch-free channel an advantage
Pricing grid, processing, collateral, derogation: six criteria to tell whether your application benefits from a branch-free bank, or will get stuck there.
Regroupement de crédits
Un regroupement de crédits dont la part des crédits immobiliers ne dépasse pas 60 % du montant total de l’opération relève du crédit à la consommation (C. consom., art. L. 314-10, L. 314-11 et R. 314-18). Le code impose alors la mention suivante sur sa publicité :
Un crédit vous engage et doit être remboursé. Vérifiez vos capacités de remboursement avant de vous engager
Your loan and your purchase
- You have a ten-day reflection period on the loan offer.
- The sale is conditional on the loan being obtained.
- If the loan is not obtained, the sums you paid the seller are refunded to you.
Mandatory legal information, in French:
L’emprunteur dispose d’un délai de réflexion de dix jours ; la vente est subordonnée à l’obtention du prêt ; si le prêt n’est pas obtenu, le vendeur doit rembourser les sommes versées.